The Crossfield Perspective

The name Crossfield is a deliberate nod to the game of lacrosse—a sport defined by speed, coordination, and a “cross-field” perspective. In the heat of play, the most effective leaders are those who can see the entire field at once, identify the strategic opening, and execute with perfect timing.

At Crossfield Strategic Partners, this same perspective guides our work. We navigate the high-speed intersection of high-net-worth planning, institutional lending, and insurance carrier relations. By maintaining a “whole field” view, we bring together producers, banks, insurers, and clients into a single, coordinated strategy. 

Our role is to provide the vision that ensures clarity, alignment, and long-term stability for every solution we architect.

Leadership & Strategy
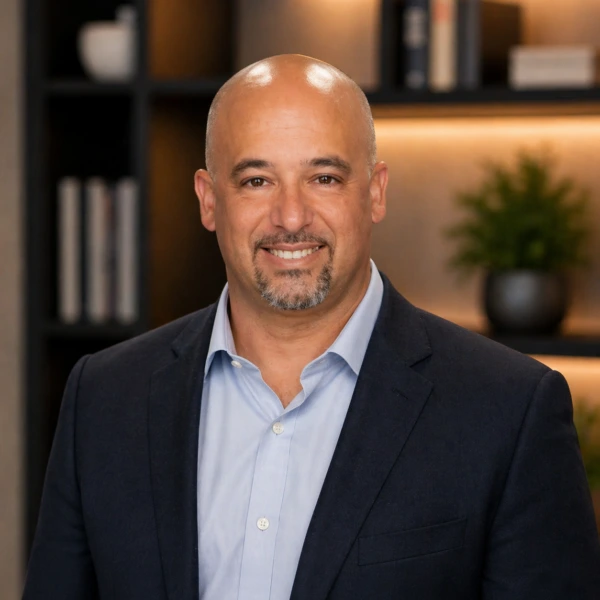
Tomer Dicturel
Tomer Dicturel
Founder & CEO
With decades of experience, Tomer is well-known for his expertise in premium finance and advanced wealth planning for high-net-worth clients. He works closely with advisors and clients to structure sophisticated strategies that integrate life insurance, banking, and tax-efficient planning. Tomer also trains and supports thousands of agents nationwide, providing the tools and frameworks needed to execute complex cases with confidence. He is a frequent speaker at AICPA and NAIFA conferences and holds both an MBA and a Doctorate in Business Administration.
Dawn Clifford, J.D.
Dawn Clifford, J.D.
SVP, Business Development
Dawn is a tax attorney with deep expertise in advanced planning and insurance, specializing in the design and implementation of sophisticated strategies for high-net-worth clients. She brings a highly technical, solutions-oriented approach to complex case design. Dawn works closely with advisors and clients to structure tailored planning strategies, ensuring they are both technically sound and effectively executed. She is known for translating complex concepts into clear, actionable guidance that drives meaningful outcomes.

Planning & Development

Caleb Smith
Caleb Smith
VP, Case Design & Planning Strategies
Caleb brings over 14 years of experience in financial services and insurance, spanning both wholesale brokerage and client-facing roles. He leverages this perspective to design and implement effective planning solutions across every stage of the process. Caleb specializes in accumulation and income planning, with deep expertise in annuities and life insurance. Caleb takes a hands-on approach, serving as a trusted partner while ensuring each client’s strategy is thoughtfully designed and fully executed.
Vivian Taylor
Vivian Taylor
Director, Talent Acquisition & Agent Development
Vivian leads the growth and development of high-performing advisors, focusing on recruiting, mentoring, and elevating their practices. She helps professionals transition into long-term, wealth-focused advisory roles through structured training and strategic coaching. A licensed educator, Vivian has trained thousands of insurance professionals across multiple organizations. Her approach blends real-world execution with high-level strategy, equipping advisors with the tools, positioning, and infrastructure needed to succeed in the affluent market.

Operations & Marketing

Michael Sciame
Michael Sciame
Operations Manager
Serving as a central point of coordination across clients, agents, and financial institutions, Michael ensures seamless execution of client cases and day-to-day operations. He manages complex scheduling, gathers documentation, and troubleshoots cases to keep processes moving efficiently. Michael’s experience as a sales agent with Humana Medicare and Allstate informs a strong understanding of client needs and policy structures. He partners closely with banking institutions, guiding cases through underwriting and approval with exceptional attention to detail.
Josh Ristovski
Josh Ristovski
Creative Marketing Specialist
With a background in advertising, Josh brings a dynamic blend of creative and operational expertise to the marketing team. He supports the full marketing lifecycle, from designing landing pages, and email campaigns to producing and editing video content that drives engagement. Josh also plays a key role in community engagement and webinar support, ensuring each touchpoint is visually compelling and strategically executed. Behind the scenes, he builds marketing automations and forms that streamline workflows and extend the team’s reach.
Matt O'Toole
Matt O’Toole
Loan Officer
Matt leads discovery calls with prospective clients, walking through their goals and financial picture to help determine how Crossfield’s premium finance and advanced planning strategies can fit their needs. His perspective is grounded in hands-on experience with the lending process, from evaluating financing options and gathering documentation through closing, where he coordinated closely with lenders, processors, and other parties to keep transactions moving efficiently. That background gives him a practical, detail-oriented approach to conversations with prospects, helping them understand not just the strategy but how it actually works in practice. A graduate of Fairleigh Dickinson University with a degree in Business Administration, Matt brings a strong work ethic and a commitment to clear, responsive communication to every client interaction.

Join the Crossfield Network

Ready to join our collaborative community?
Common Questions

Frequently Asked Questions

Answers to the questions we hear most often about premium finance and how Crossfield structures advanced insurance strategies.

What is premium finance life insurance?

Premium finance is a strategy where a policyholder borrows some or all of the funds needed to pay premiums on a life insurance policy, rather than paying premiums directly out of pocket. It's typically used by business owners and high-earning families who want to secure significant coverage without needing to sell or disrupt other assets they hold. Crossfield Strategic Partners is a licensed insurance agency that designs and structures these arrangements in coordination with lending institutions and issuing carriers.

Who is premium finance typically designed for?

Premium finance strategies are generally suited to business owners and high-earning families with significant assets concentrated in illiquid holdings — such as private businesses or real estate — who want to secure life insurance protection without selling or repositioning those core assets.

Is premium finance the same as taking out a loan against my policy?

No. A policy loan is borrowed against the cash value of an existing policy. Premium finance is a separate arrangement, typically with a third-party lender, used to fund premium payments on a new or existing policy from the outset. The two involve different collateral structures, lenders, and risk considerations.

What are the risks of premium finance?

As with any financing arrangement, premium finance involves interest-rate risk, lender risk, and policy-performance risk. Structures should be conservatively designed and regularly reviewed. Any illustrated policy performance is based on non-guaranteed assumptions; actual results will vary. Crossfield stress-tests every strategy against realistic, time-tested assumptions rather than optimistic projections, and works with clients' independent tax and legal advisors to evaluate whether a strategy fits their broader financial picture.

How is the loan for premium finance repaid?

Repayment structures vary by arrangement and are defined at the outset — Crossfield designs each strategy with a clear, structured repayment plan rather than an open-ended obligation. Specific repayment terms depend on the lender, the policy structure, and the client's individual circumstances.

Are the death benefits from a life insurance policy taxable?

Death benefits are generally received income tax-free under IRC §101(a). However, tax treatment depends on individual policy structure and circumstances, and Crossfield does not provide legal or tax advice — clients should consult their own independent tax and legal professionals regarding their specific situation.

How does premium finance help with estate and legacy planning?

Life insurance funded through premium finance can help provide funds available at death to cover estate tax obligations, support a smooth transfer of assets across generations, and reduce the need to sell or liquidate illiquid assets like a family business or real estate holdings to cover tax obligations. Tax outcomes depend on individual circumstances — clients should consult their own independent tax and legal advisors.

Does Crossfield work directly with individuals, or only through producers?

Crossfield Strategic Partners is a licensed, boutique insurance agency working with both clients directly and a network of licensed insurance producers. Our producer network allows us to bring these advanced strategies to a broader group of business owners and high-earning families through experienced, independently licensed professionals.

What carriers and lenders does Crossfield work with?

Crossfield maintains long-standing relationships with a select group of leading insurance carriers and lending institutions, chosen specifically for their ability to support sophisticated, insurance-based financing structures.

How do I know if premium finance is right for my situation?

Every client's financial picture is different. Crossfield's approach starts with understanding your specific needs, asset composition, and long-term goals before recommending any strategy — and every solution is reviewed against conservative, realistic assumptions rather than best-case projections. The best next step is a direct conversation with our team.

Insurance products are fixed or indexed and are not an investment in the equity markets. Performance is subject to the claims-paying ability of the issuing carrier. Death benefits are generally received income tax-free under IRC §101(a). Policy loans and withdrawals are generally not subject to federal income tax provided the policy is not a Modified Endowment Contract (MEC) under §7702A and remains in force. Outstanding loans and withdrawals will reduce the policy's cash value and death benefit. A policy lapse or surrender with an outstanding loan may result in taxable income. Crossfield Strategic Partners (CSP) does not provide legal or tax advice; consult with your independent professional advisors regarding your specific situation.